Week 30, 2026 Market Update | TE Connector Allocation, Xilinx 70-Week Lead Times, Supplier Price Adjustments
Supply pressure continues to expand across connectors, semiconductors, and power components. This week's update covers TE Connectivity supply constraints, AMD/Xilinx FPGA lead-time extensions, JST connector discontinuation, and multiple supplier price adjustments across semiconductor and passive component markets.
AI infrastructure demand remains a key driver influencing semiconductor capacity allocation and power component requirements.
Below is a condensed view by manufacturer.
TE Connectivity — Automotive connector supply remains tight
TE Connectivity continues to experience supply pressure across automotive and communication connector categories.
According to distributor feedback, automotive connector products have entered manufacturer-controlled allocation management, with delivery cycles extending due to concentrated downstream demand and limited short-term capacity availability.
Affected part numbers include:
1. 2318579-2
2. 1367073-1
3. 1551920-2
4. 2170088-1
5. 6469 series
6. ZD series
Procurement teams should closely monitor allocation status and review sourcing plans for affected BOMs.
AMD/Xilinx — FPGA lead times extend to around 70 weeks
Traditional Xilinx FPGA supply remains constrained as AMD continues expanding its AI and Adaptive Computing business.
Current market conditions:
- Mainstream Xilinx lead times have extended to around 70 weeks, compared with approximately 50 weeks previously.
- XC7A and XC7Z series remain among the most requested products.
- Limited inventory availability continues to push spot market prices higher.
Popular models include:
1. XC7Z020-2CLG484I
2. XC7A75T-2FGG484I
Short-term supply pressure is expected to continue, with inventory availability becoming increasingly important for FPGA sourcing.
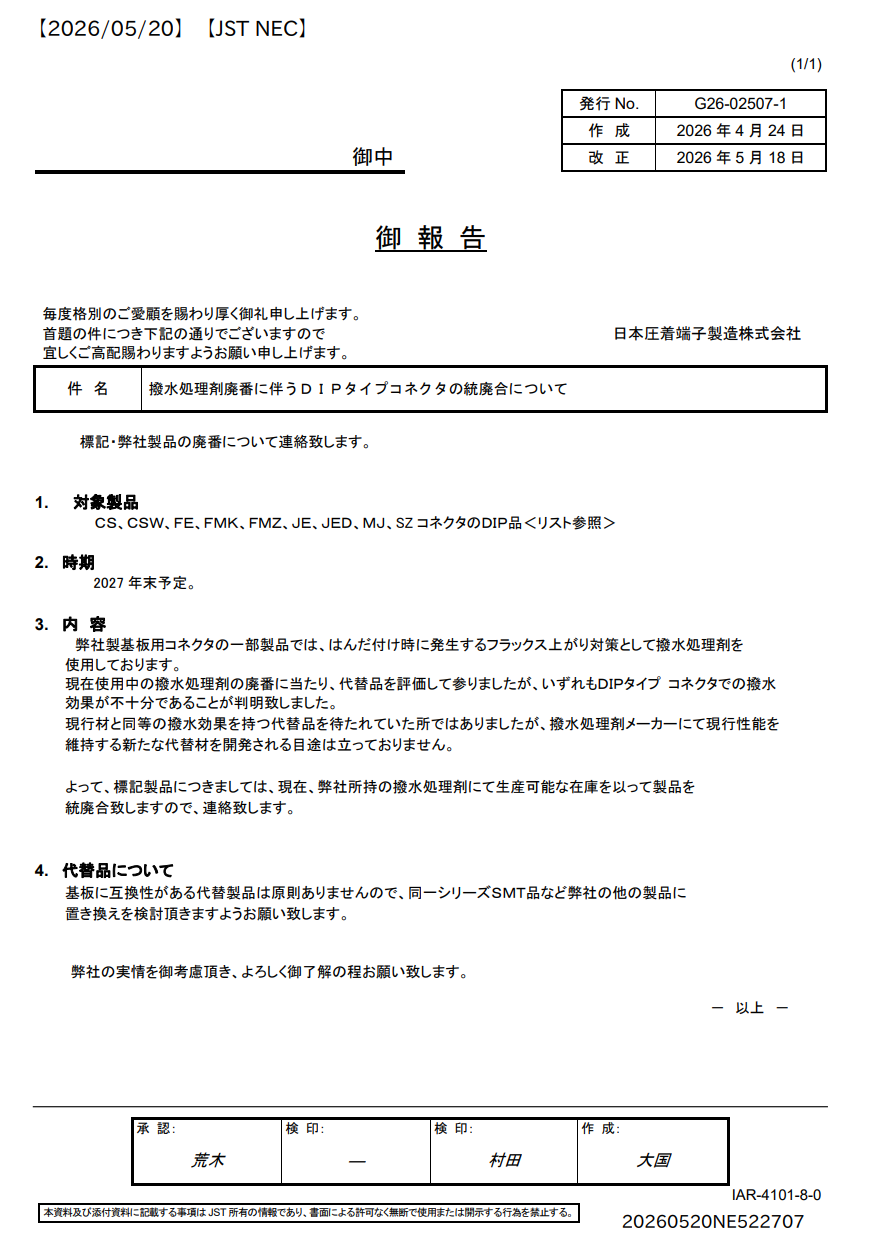
JST — Nine DIP through-hole connector series to discontinue by end-2027
JST announced the discontinuation of nine DIP through-hole connector series due to the discontinuation of a waterproof treatment material used in production.
Affected series include:
CS, CSW, FE, FMK, FMZ, JE, JED, MJ, and SZ.
The discontinuation notice was issued on June 2, 2026, with production scheduled to end by the end of 2027.
The change covers all affected pin configurations, with related headers, housings, terminals, and waterproof components also being phased out.
Customers using these connectors in industrial equipment, appliances, and outdoor applications should review future demand and inventory planning.
Qorvo — Selected products and product families to receive price adjustments from Aug 24
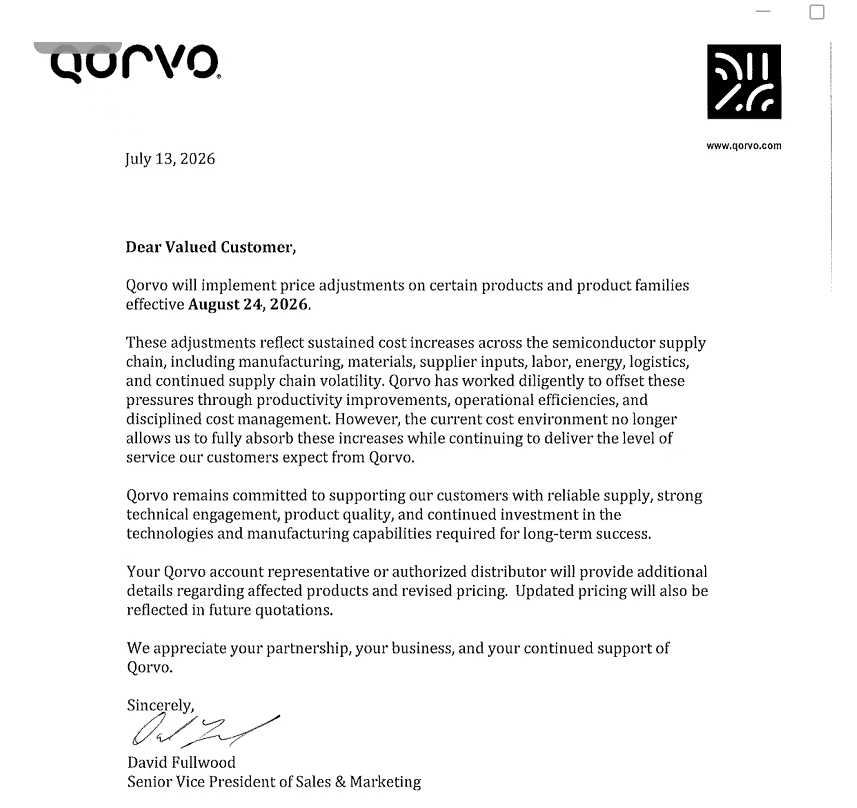
Qorvo announced price adjustments for selected products and product families effective August 24, 2026.
The company cited continued cost increases across the semiconductor supply chain, including:
1. Wafer manufacturing
2. Raw materials
3. Labor
4. Energy
5. Logistics
Specific affected products and revised pricing details will be communicated through account channels.
Rubycon — Aluminum electrolytic capacitor prices to be revised from Aug 1
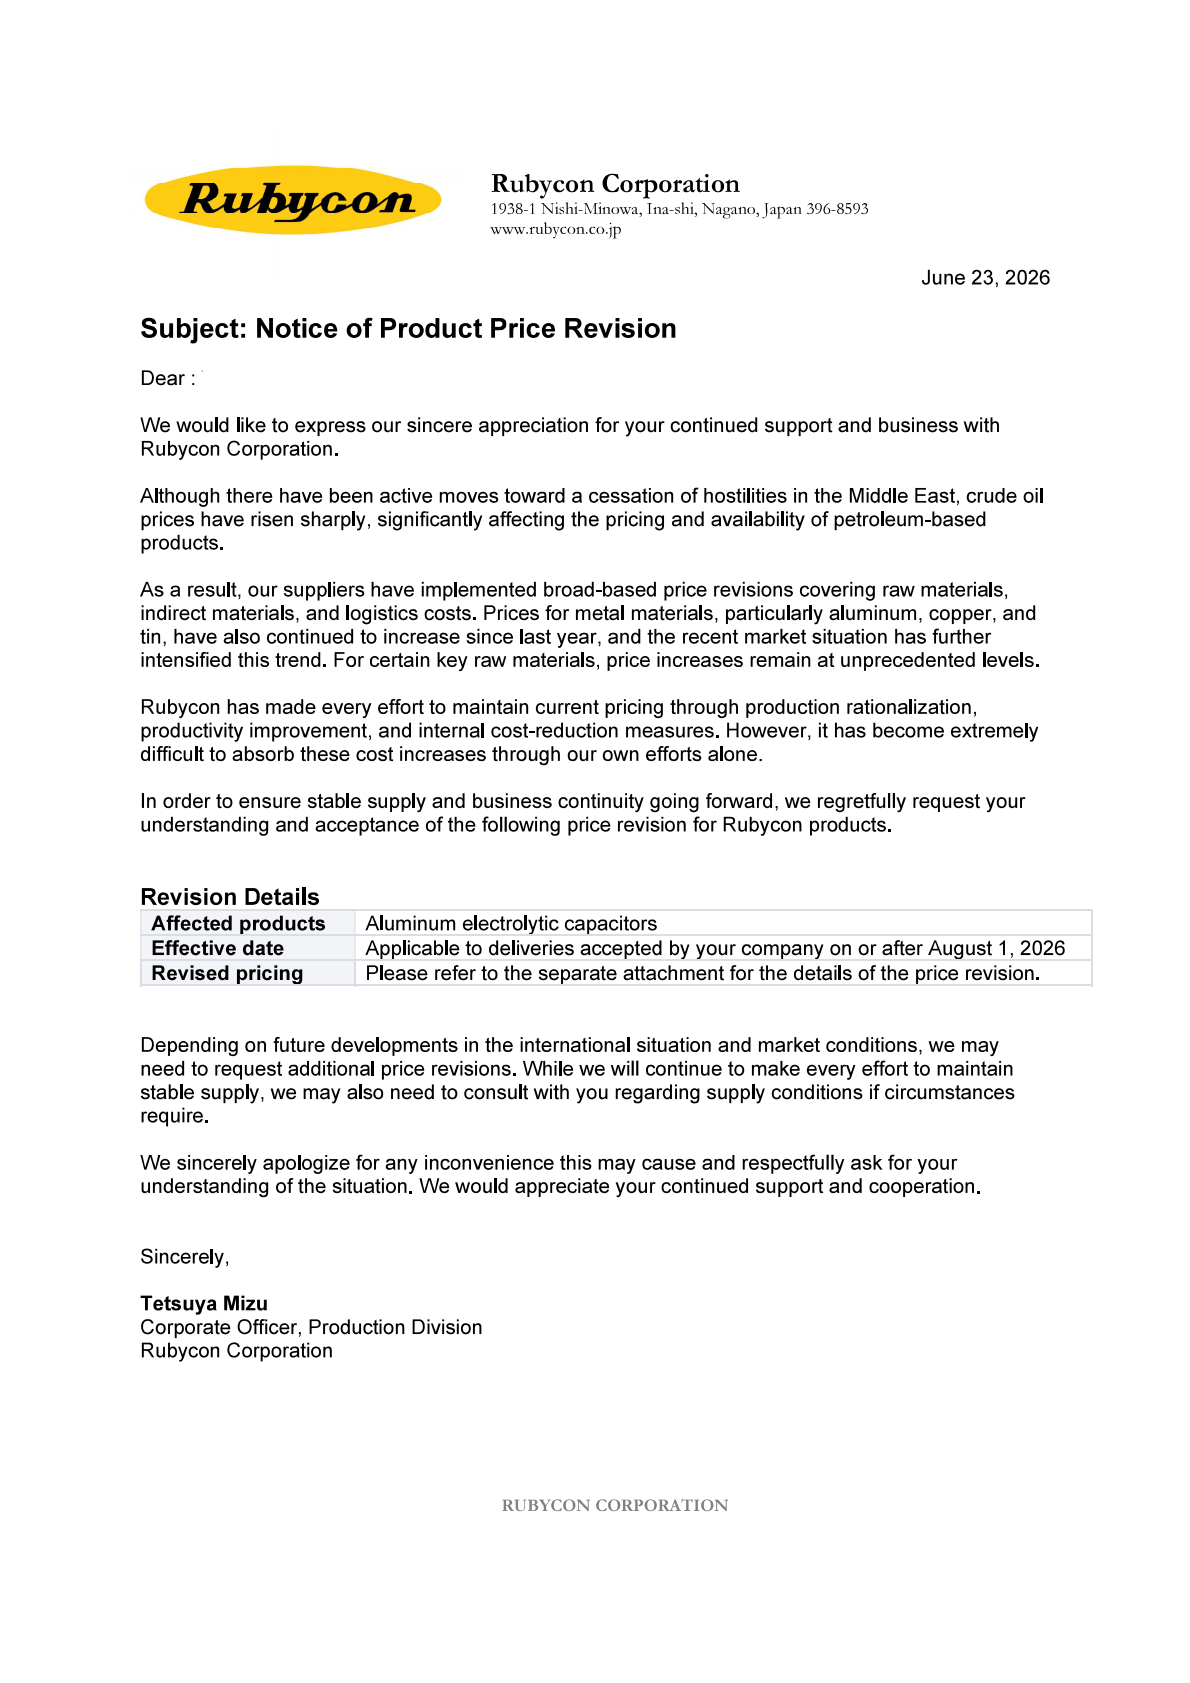
Rubycon announced a price revision for general-purpose aluminum electrolytic capacitors.
The adjustment applies to shipments from:
August 1, 2026
The company attributed the revision to rising petroleum-related costs, raw materials, and logistics expenses.
Detailed adjustment levels will be provided separately.
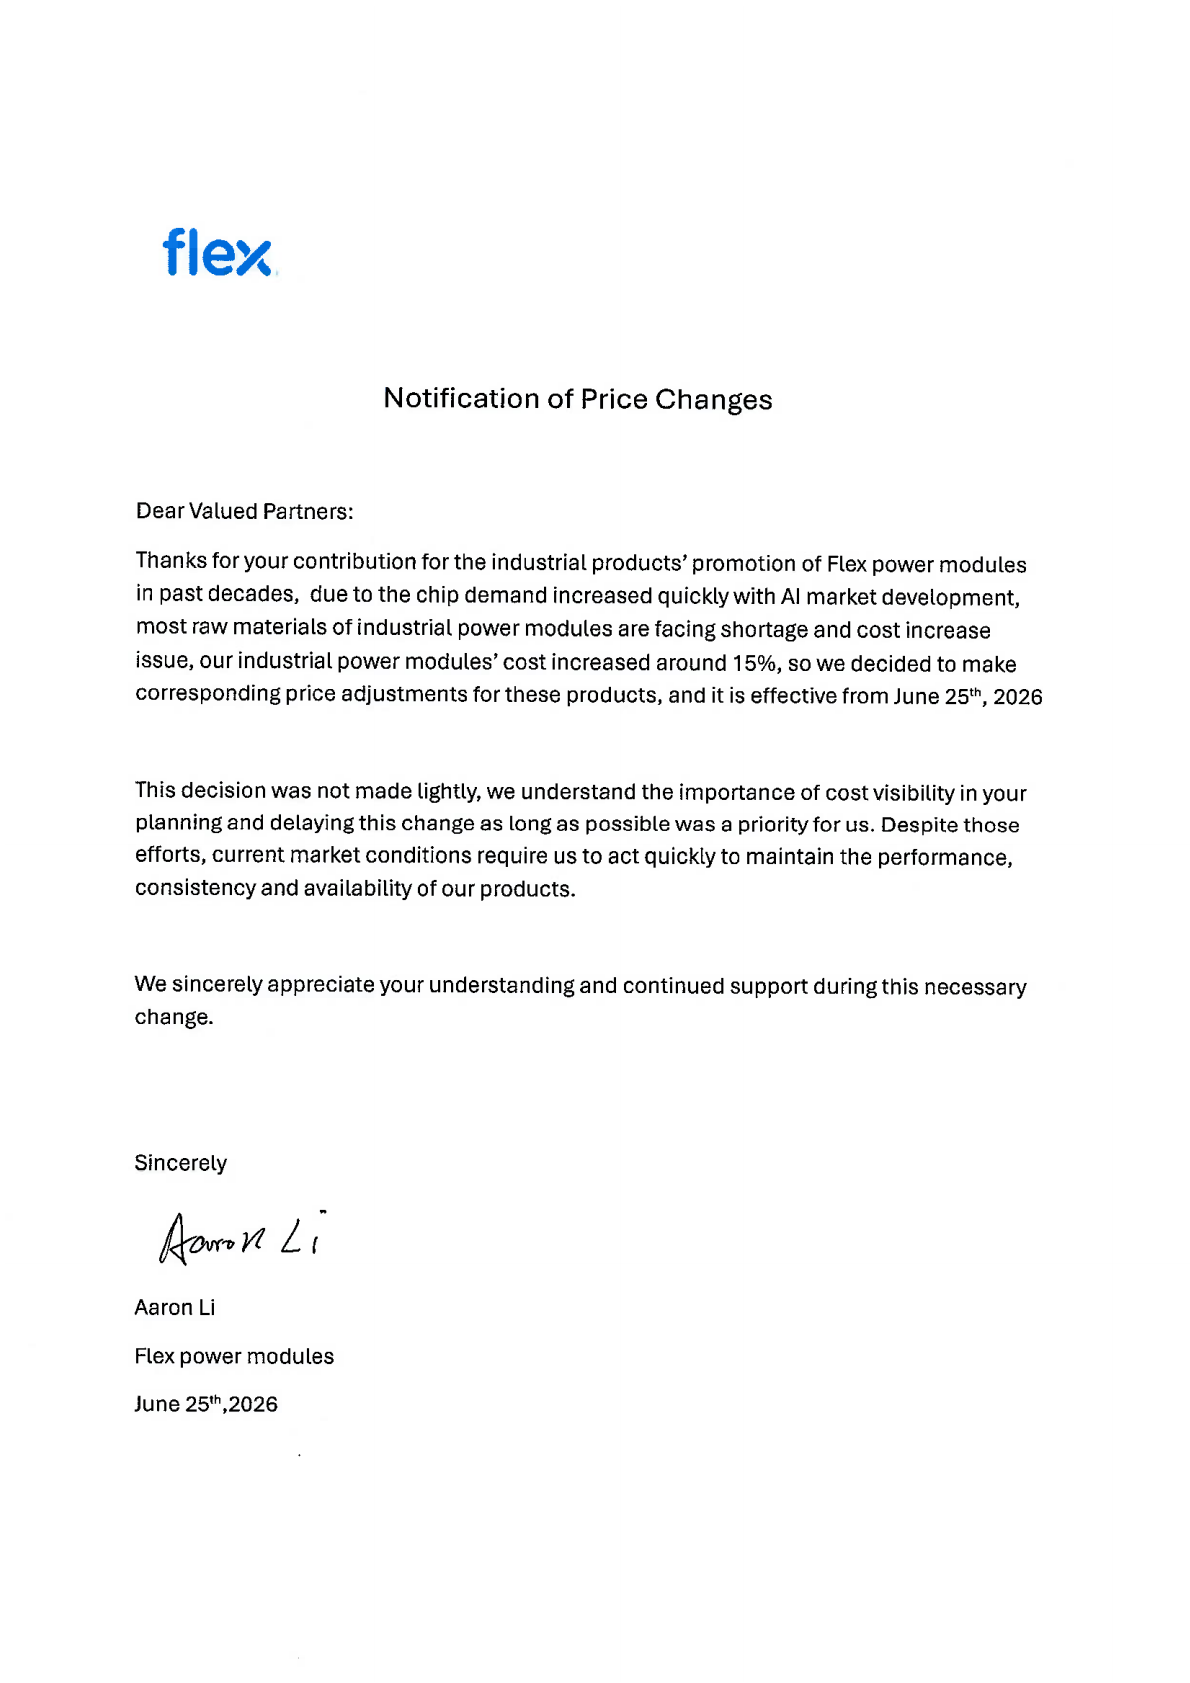
Flex Power Modules — Industrial power module prices increase approximately 15%
Flex Power Modules announced an approximately 15% price increase for industrial power modules effective June 25, 2026.
The company cited rising material costs and increased demand pressure from AI infrastructure development.
Flex Power Modules products are widely used in:
1. AI data centers
2. Cloud computing
3. Telecommunications
4. Industrial applications
ADI — Supply tightness continues after July alert
ADI issued a supply-tightness notification on July 3, 2026, confirming extended lead times for selected products.
Some products are currently facing:
6+ months lead times
Market quotations have become shorter in validity as supply conditions remain tight.
ADI also completed the acquisition of Empower Semiconductor on July 8, strengthening its AI power management capabilities.
STMicroelectronics — Selected MCU lead times reach 52 weeks
Selected STMicroelectronics MCU products continue to experience extended lead times, with some models reaching:
52 weeks
Distribution channels have started collecting customer demand forecasts for 2027 to support supply planning.
Texas Instruments — Manufacturing transition impacts lead times
Texas Instruments is undergoing an 8-inch to 12-inch wafer production transition.
Current lead times are generally reported at:
12–20 weeks
AI-related demand continues to influence mature-node capacity allocation, gradually affecting industrial and general-purpose applications.
Industry & Product News
NVIDIA — Rubin AI platform enters HBM4 supply phase
NVIDIA's next-generation Rubin AI GPU platform has entered the HBM4 supply phase.
HBM remains one of the most critical bottleneck components in AI computing infrastructure, with memory availability expected to influence future AI server delivery schedules.
Microchip — VectorBlox 3.0 AI Accelerator SDK released
Microchip introduced VectorBlox 3.0 AI Accelerator SDK for FPGA-based neural network inference.
The solution targets low-power, high-reliability applications and supports PolarFire FPGA families.
Nexperia & Swissbit — AI and cloud security platform partnership
Swissbit AG and Nexperia BV announced a partnership to develop secure, high-reliability platforms for AI, cloud computing, and server applications.
The collaboration combines Swissbit's secure storage technology with Nexperia's semiconductor expertise to support next-generation AI accelerators, data centers, and edge computing systems.